Germany’s construction market still stalling at the bottom
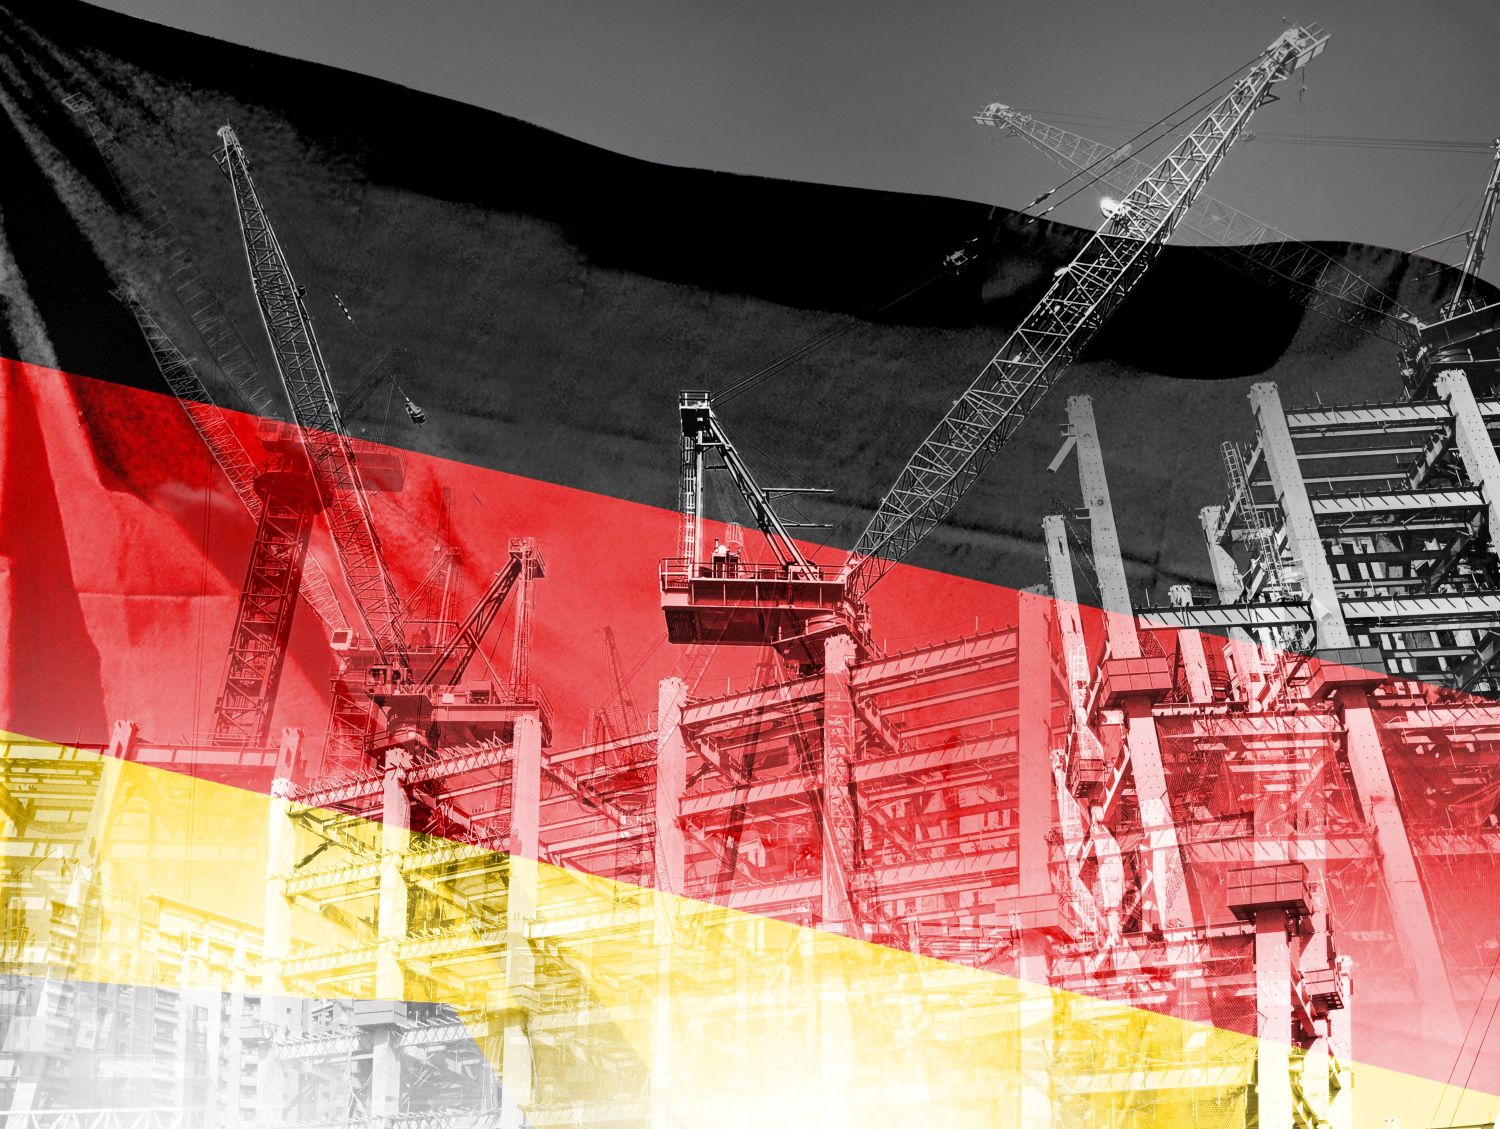
Germany’s construction market continues its prolonged slump. While June 2025 saw a modest 7.9% rise in residential building permits compared to the previous year, this uplift follows rock-bottom levels of activity - with no sign of real recovery – according to industry leaders who warn that permits are still too low to drive meaningful growth across the sector.
This is the view of the ZDB industry association, who say that construction revenues are projected to decline further in 2025, marking a fifth consecutive year of falling activity. For the first half of the year, sales are estimated at €159.3 billion - down 2% nominally, or about 4% in real terms from 2023 levels.
ZDB Industry stands for the Central Association of the German Construction Industry. It is one of the leading trade associations representing small and medium-sized construction companies in Germany. The ZDB lobbies on behalf of its members, provides economic forecasts and plays a major role in policy discussions with the German government on housing, infrastructure and regulatory matters – so it is an organisation that knows what it is talking about.
Meeting housing demand remains a critical issue. The Federal Institute for Research (BBSR) estimates that Germany needs to build 320,000 new apartments annually until 2030, yet only 216,000 were approved in 2024 - the lowest number since 2010.
Europe’s mixed outlook
While Germany’s construction output is expected to shrink approximately 2.5% in 2025. France isn’t faring much better, with forecasts signalling a 1% downturn in 2025. The Netherlands shows signs of recovery, with modest growth of around 1.5% expected. Spain stands out with a stronger forecast - 1.5% growth in 2024 and continued momentum into 2025 - thanks in part to EU recovery funds and residential investment.
Market forecasts by Bain & Company anticipate Germany will lag behind in recovery, growing just 0 -2% in residential construction between 2025 and 2027, compared to 3 - 5% in the UK and 5 - 7% in France. Real growth forecasts from BMI align with this, projecting Germany’s construction CAGR at 1.7%, below the wider European average of 2.1% from 2023 to 2027.
Related read: Understanding the hidden costs of failed project bids
The UK
The UK is expected to lead Europe’s construction rebound with a 2 - 4% CAGR between 2025 and 2027. That aligns with additional infrastructure investments into landmark projects like Crossrail and HS2 and a public-sector push into nuclear power and renewables.
United States
In the U.S., construction growth has slowed due to tariffs, increased interest rates and weak business sentiment. Output forecasts for 2025 estimate only 0.7% growth overall, with non-residential contraction hitting around - 1.4%. Residential construction grows slightly (around 0.9%) and civil engineering continues to show relative strength (3.4%).
So what do we know
- Germany sits in a deep trough: housing permit activity is at stagnation, construction volumes continue to decline, and major housing targets are unmet.
- Spain and the Netherlands are emerging as near-term winners in Europe, whereas France and Germany lag behind.
- The UK holds stronger prospects - the planned projects and modest recovery forecast point to steadier growth.
- The U.S. shows resilience in infrastructure, while residential and commercial segments face cooling demand.
Germany’s current weak construction performance is partly due to sustained headwinds—high costs, energy uncertainties and cautious investment - making it the exception among Western peers who are at least beginning to move into recovery mode.
However, Germany’s construction market still stands out in Europe for its resilience, technological innovation and strong regulatory framework, as championed by associations like the ZDB. While it faces challenges such as material costs, labour shortages and the need for sustainable building practices, it consistently compares favourably with other Western economies in terms of efficiency, project quality and long-term planning.
For investors, contractors, and stakeholders looking to understand or enter the European construction market, Germany continues to offer a model of stability and opportunity -proving that careful regulation, industry collaboration and forward-thinking policy can drive growth while maintaining high standards.
Additional Blogs

Commercial lease dilapidations and why leaving it until lease expiry is a costly mistake
For many businesses, the condition of a commercial property only becomes a serious issue when the end of the lease starts approaching. Until then, repairs are often treated as operational matters:...
Read moreHow Technical Training Prepares the Next Generation of Construction Workers
The construction industry is changing fast. Modern jobsites demand more than strong hands and a willingness to work hard. You need technical knowledge, digital skills and safety training to keep up...
Read more
Moving beyond traditional telematics with safety-first connected fleet platforms
For many years, traditional telematics delivered a wealth of operational insight, from vehicle tracking to driver behaviour monitoring. But as construction programmes grow more complex, urban sites...
Read more